IB Mathematics: Applications and Interpretation SL — Topic 1 Number and algebra
Financial Mathematics
Understand the model. Set up the equation. Solve with technology.
Learning goal
Calculate balances, deposits, rates and times; interpret growth in purchasing power.
Syllabus link
AI SL SL 1.4: compound interest, annual depreciation and real investment value with inflation.
Technology
Use the Finance Solver for standard compound-interest problems. Use Scratchpad calculations for the inflation example.
Big idea
Grow the investment, then divide by the price-growth multiplier to express buying power in today's money.
Simple interest: why does the formula work?
The principal, \(u_0\), is the original amount invested. The balance after \(n\) years is \(u_n\). At \(n=0\), no interest has yet been earned.
Start with a numerical example
Question
Invest $1000 at 5% simple interest per year for three years. Find the final balance.
Solution
With simple interest, every year’s interest is calculated from the original $1000, even when the balance has grown. \[\text{Interest each year}=\frac{5}{100}\times1000=\$50.\]
After three years, the total interest is \(3\times\$50=\$150\). The final balance is \(\$1000+\$150=\boxed{\$1150}\).
Now use the same reasoning to build the formula
Let the simple-interest rate be \(r\%\) per year and the time be \(n\) years. Since \(r\%=r/100\):
Find one year’s interest: \(\displaystyle u_0\times\frac{r}{100}\).
Multiply by the number of years: total interest \(\displaystyle=n\times u_0\times\frac{r}{100}\).
Add the original amount: \[u_n=\underbrace{u_0}_{\text{original amount}}+\underbrace{n\times u_0\times\frac{r}{100}}_{\text{total interest}} =\boxed{u_0\left(1+\frac{nr}{100}\right)}.\]
Taking \(u_0\) outside the brackets gives the last form. The 1 keeps the original amount; the \(nr/100\) adds the interest earned over \(n\) years.
Booklet: not given separately; this is an arithmetic model starting at \(u_0\).
Use it for the same example: \(u_3=1000(1+3\times5/100)=\$1150\).
The same simple-interest formula using PV and FV
You may prefer these financial labels:
PV = present value: the original amount invested, before any interest. This is \(u_0\).
FV = future value: the final balance after \(n\) years, including the interest. This is \(u_n\).
With \(r\%\) simple interest per year: \[\underbrace{\mathrm{FV}}_{\text{final balance}} =\underbrace{\mathrm{PV}}_{\text{original amount}} +\underbrace{\mathrm{PV}\times\frac{r}{100}\times n}_{\text{total interest}}, \qquad \boxed{\mathrm{FV}=\mathrm{PV}\left(1+\frac{nr}{100}\right)}.\] This is the same formula with different labels. Use \(r=5\) for 5%, and use \(n\) in years. PV and FV are positive balances here; Finance Solver cash-flow signs are explained in the cash-flow signs section.
Booklet: neither form is given separately in the formula booklet.
The same example using PV and FV
Question
Invest $1000 at 5% simple interest per year for three years. Find (a) the total interest and (b) the future value.
Solution
Here \(\mathrm{PV}=1000\), \(r=5\) and \(n=3\). \[\text{(a) Total interest}=\mathrm{PV}\times\frac{r}{100}\times n =1000\times\frac{5}{100}\times3=\boxed{\$150}.\] \[\text{(b) }\mathrm{FV}=\mathrm{PV}\left(1+\frac{nr}{100}\right) =1000\left(1+\frac{3\times5}{100}\right)=\boxed{\$1150}.\] On a Calculator page enter
1000*(1+3*5/100)
This gives the final balance, including the original deposit. The interest alone is \(\mathrm{FV}-\mathrm{PV}=1150-1000=\$150\).
| Years completed | 0 | 1 | 2 | 3 |
|---|---|---|---|---|
| Total interest ($) | 0 | 50 | 100 | 150 |
| Balance ($) | 1000 | 1050 | 1100 | 1150 |
What changes with compound interest?
With compound interest, each year’s interest is calculated from the current balance. Earlier interest earns interest too. Example. Start with $1000 at 5%, compounded annually. Each year, find 5% of that year’s starting balance, then add it:
| Year | Starting balance ($) | Interest added ($) | Year-end balance ($) |
|---|---|---|---|
| 1 | 1000 | \(1000\times0.05=50\) | 1050 |
| 2 | 1050 | \(1050\times0.05=52.50\) | 1102.50 |
| 3 | 1102.50 | \(1102.50\times0.05=55.125\) | 1157.625 |
The final balance is $1157.63, compared with $1150 for simple interest. The percentage stays at 5%, but the amount of interest grows. Keep the unrounded values until the final answer.
Our approach: write the model and substitute the data before using the calculator. Keep full precision until the final answer. Unless stated, assume no further transactions, fees or taxes and a constant rate.
Compound interest: build the multiplier, then the formula
Step 1 | Adding a percentage gives a multiplier
Let \(V\) be the current balance and let the annual interest rate be \(r\%\). One year’s interest is \(V\times r/100\), so \[\begin{aligned} \text{Balance after one year} &=\text{current balance}+\text{interest}\\ &=V+V\times\frac{r}{100}\\ &=V\left(1+\frac{r}{100}\right). \end{aligned}\] We have taken the common factor \(V\) outside the brackets. Therefore the annual multiplier is \(\boxed{q=1+r/100}\). The 1 keeps the current balance; \(r/100\) adds the interest. Example. At 5%, \(q=1+5/100=1.05\). Thus \(1000+1000\times0.05\) is the same as \(1000\times1.05=1050\).
Step 2 | Repeated multiplication gives the power
Start with PV. For annual compounding, multiply the new balance by \(q\) each year: \[\begin{aligned} \text{After 1 year:}\quad &\mathrm{PV}\times q,\\ \text{after 2 years:}\quad &(\mathrm{PV}\times q)\times q=\mathrm{PV}\times q^2,\\ \text{after 3 years:}\quad &(\mathrm{PV}\times q^2)\times q=\mathrm{PV}\times q^3. \end{aligned}\] After \(n\) years there are \(n\) multiplications by \(q\), so \[\boxed{\mathrm{FV}=\mathrm{PV}\,q^n=\mathrm{PV}\left(1+\frac{r}{100}\right)^n}.\] In sequence notation this is \(u_n=u_0q^n\), with \(u_0=\mathrm{PV}\) and \(u_n=\mathrm{FV}\).
Booklet: annual case of the compound-interest formula in 1.4; also the 1.3 geometric model, starting at \(u_0\).
Example. For $1000 at 5% compounded annually for three years, \(\mathrm{FV}=1000(1.05)^3=1157.625\approx\$1157.63\), matching the table.
Step 3 | More than one compounding period per year
If the nominal annual rate is \(r\%\) and interest is compounded \(k\) times per year:
Divide the annual rate by \(k\): the rate per period is \(r/k\%\).
The multiplier per period is \(\displaystyle 1+\frac{r/k}{100}=1+\frac{r}{100k}\).
In \(n\) years there are \(\boldsymbol{kn}\) periods, so apply that multiplier \(kn\) times.
\[\mathrm{FV}=\mathrm{PV}\times(\text{multiplier per period})^{\text{number of periods}} \quad\Longrightarrow\quad \boxed{\mathrm{FV}=\mathrm{PV}\left(1+\frac{r}{100k}\right)^{kn}}.\]
Booklet: this compound-interest formula is given in section 1.4. PV is the initial amount; FV is the final balance; \(n\) is time in years.
Example. At 4.8% compounded monthly, \(k=12\): each month earns \(4.8/12=0.4\%\), giving multiplier \(1+0.4/100=1.004\). Three years means \(12\times3=36\) periods, so $5000 grows to \(5000(1.004)^{36}\approx\$5772.76\).
Compound interest | Apply the formula with a calculator
\[\mathrm{FV}=\mathrm{PV}\left(1+\frac{r}{100k}\right)^{kn}\]
Booklet: given in 1.4. Use \(r\) as a percentage, \(k\) periods per year and \(n\) years.
Worked example 1 | Annual compounding
Question
$3000 earns 4.5% per year, compounded annually, for five years. Find (a) its final balance and (b) the interest earned.
Solution
Here PV \(=3000\), \(r=4.5\), \(k=1\) and \(n=5\). \[\text{(a) }\mathrm{FV}=3000\left(1+\frac{4.5}{100}\right)^5=3738.545812\ldots\approx\boxed{\$3738.55}.\] (b) Interest earned \(=\mathrm{FV}-\mathrm{PV}=3738.545812\ldots-3000\approx\boxed{\$738.55}\).
Booklet: interest earned is not given as a separate formula.
Worked example 2 | Monthly compounding
Question
$5000 earns a nominal annual rate of 4.8%, compounded monthly, for three years. Find (a) the final balance and (b) the interest earned.
Solution
Monthly means \(k=12\). The multiplier is \(1+4.8/1200=1.004\) and there are \(kn=12\times3=36\) periods. \[\text{(a) }\mathrm{FV}=5000\left(1+\frac{4.8}{100\times12}\right)^{36}=5772.762169\ldots\approx\boxed{\$5772.76}.\] (b) Interest earned \(=5772.762169\ldots-5000\approx\boxed{\$772.76}\).
On a Calculator page enter
5000*(1+4.8/1200)^36
Press Enter; use Ctrl+Enter if a decimal approximation is needed.
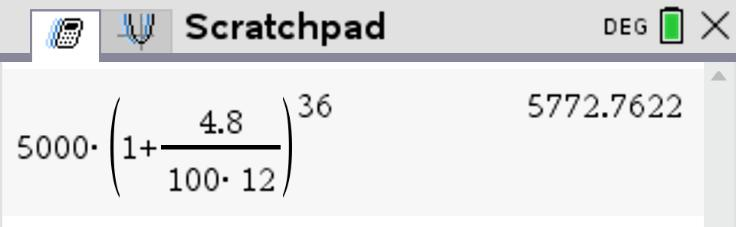
TI-Nspire CX: the displayed result rounds to $5772.76.
Other frequencies: annually \(k=1\); half-yearly \(k=2\); quarterly \(k=4\); monthly \(k=12\). For 2.5 years with monthly compounding, the exponent is \(12\times2.5=30\).
Finance Solver | Signs and access
The Finance Solver uses cash-flow signs. Take our point of view: a payment leaving us is negative; money coming to us is positive.
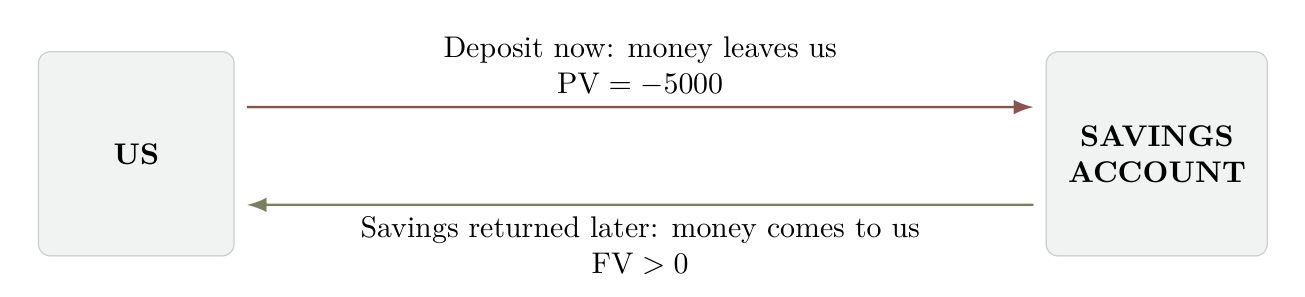
A negative PV does not mean a negative balance
If you invest $5000, enter \(\mathrm{PV}=-5000\). Your account still holds $5000. The minus sign records the direction of the payment.
For these single-deposit investments, PV and FV have opposite signs. FV represents what you could receive if you withdrew the savings then.
Open the Finance Solver
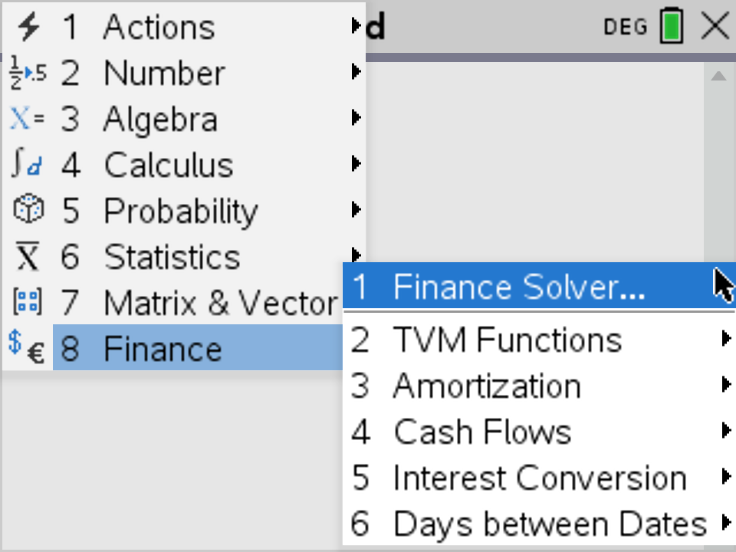
Open a Calculator page.
Press Menu.
Select 8: Finance, then 1: Finance Solver.
Menu numbering can vary with software; follow the menu names.
The routine for every Finance Solver question
Identify the unknown: FV, PV, I(%) or N.
Enter all known values. Use Tab to move between fields. Check the lower settings too.
Return to the unknown field and press Enter. A displayed zero or old value is not the answer until you solve that field.
Interpret the result: include money, a percentage or the correct time unit.
In your written working: record the solver inputs, the field you solved and an answer sentence. The calculator performs the calculation; your working shows the method.
Finance Solver | Fields and periods
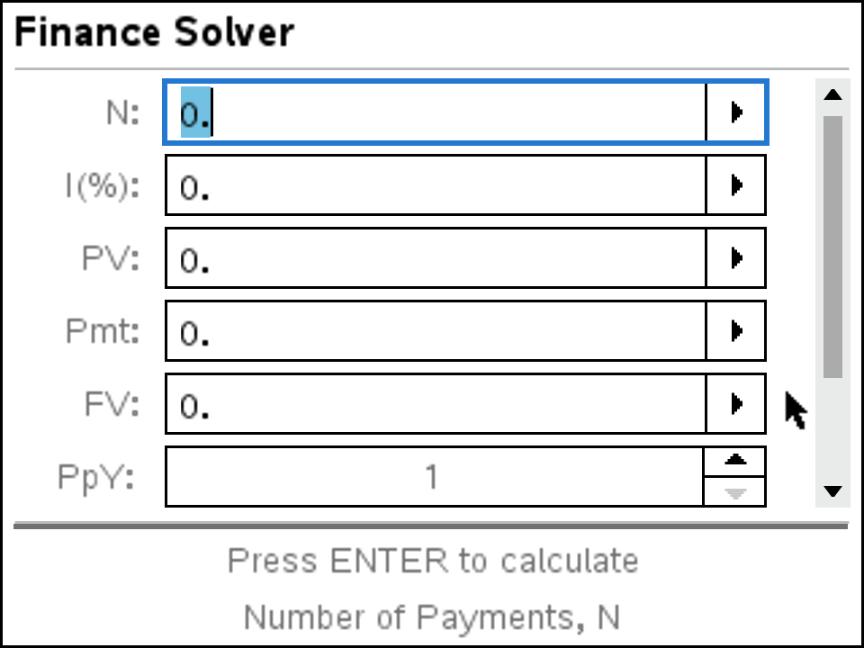
Upper fields.
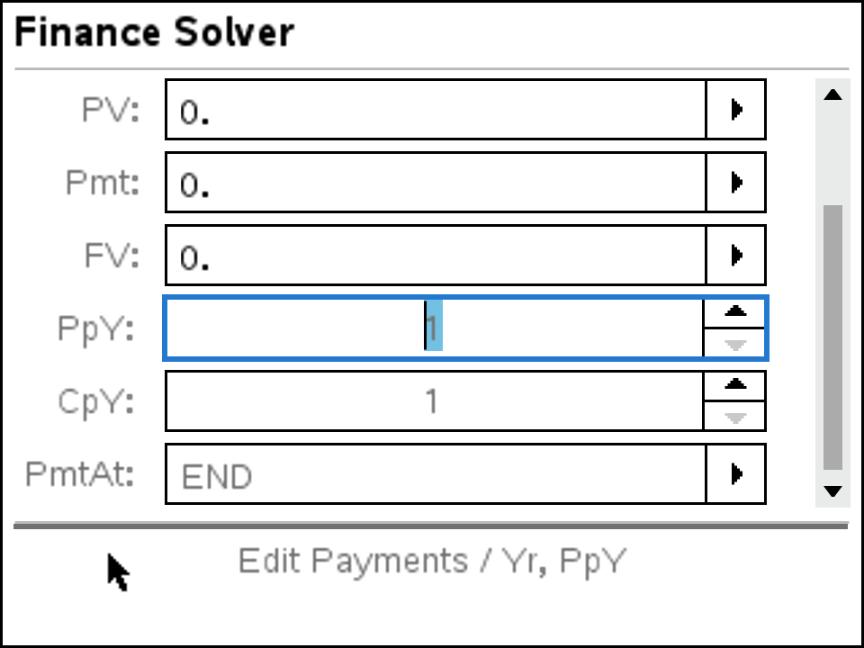
Scroll down to check all settings.
| Field | What to enter |
|---|---|
N |
Total periods. With our settings below: years, half-years, quarters or months. |
I(%) |
The nominal annual percentage rate. For 4.8%, enter \(4.8\), not \(0.048\). |
PV |
Initial cash flow. A savings deposit is negative. |
Pmt |
Regular payment each period: 0 throughout this handout. |
FV |
Final cash flow. Savings received are positive. |
PpY |
Payments per year. With Pmt = 0, this sets the unit counted by N. |
CpY |
Compounding periods per year. We set PpY equal to CpY here. |
PmtAt |
Choose END. Timing has no effect when Pmt = 0. |
| Compounding | PpY = CpY | N for \(n\) years | Example: 3 years |
|---|---|---|---|
| Annually | 1 | \(n\) | 3 |
| Half-yearly | 2 | \(2n\) | 6 |
| Quarterly | 4 | \(4n\) | 12 |
| Monthly | 12 | \(12n\) | 36 |
Keep the annual rate; change the period settings
At 4.8% compounded monthly, use I(%) = 4.8 and PpY = CpY = 12. The solver handles the monthly rate. Do not divide I(%) by 12.
Previous entries may remain: recheck every field for every new question.
Choose the field to solve
| What is the question asking for? | Solve this field |
|---|---|
| The amount invested now | PV |
| The final balance | FV |
| The nominal annual interest rate | I(%) |
| The time, counted in periods | N |
The Finance Solver handles the compound-interest calculation. We still write the model, enter the correct settings and interpret its answer.
Find the initial deposit | Solve PV
Worked example 3 | How much should be invested now?
Question
An investment must grow to $8000 in five years. The nominal annual rate is 3.6%, compounded quarterly. Find the initial deposit to the nearest cent.
Solution
Let \(x\) be the initial deposit, in dollars. Use \(\mathrm{FV}=\mathrm{PV}(1+r/(100k))^{kn}\) with \(r=3.6\), \(k=4\) and \(n=5\): \[8000=x\left(1+\frac{3.6}{100\times4}\right)^{4\times5}=x(1.009)^{20}.\]
Booklet: the compound-interest formula is given in 1.4. Here \(x\) is the positive amount invested.
TI-Nspire CX | Finance Solver
There are \(4\times5=\textbf{20 quarters}\). Set PpY = CpY = 4 and Pmt = 0. We know FV and need PV. Enter the known values, then solve the PV field.
| N | I(%) | PV | Pmt | FV | PpY | CpY | PmtAt |
| 20 | 3.6 | solve | 0 | 8000 | 4 | 4 | END |
1. Enter the known values
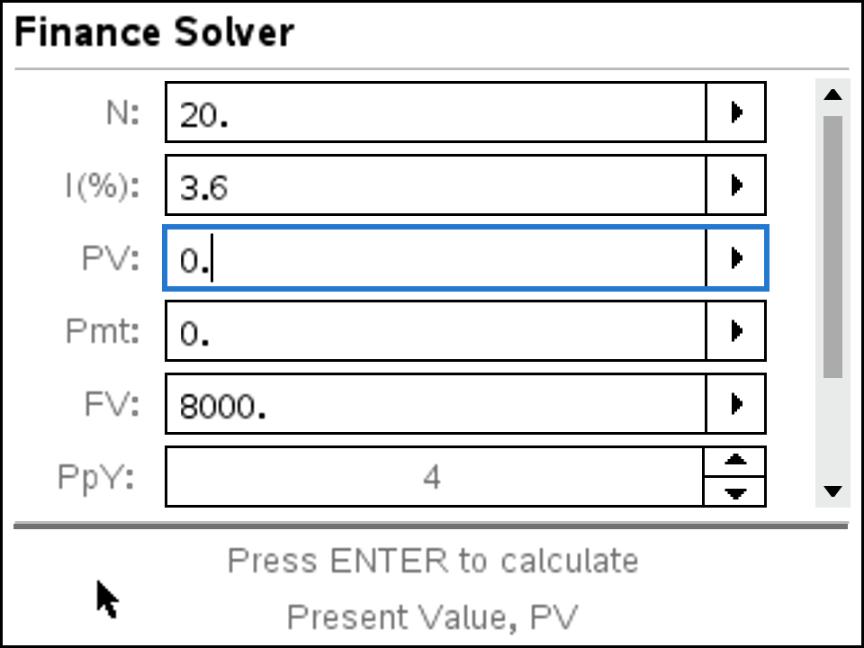
2. Check the lower settings
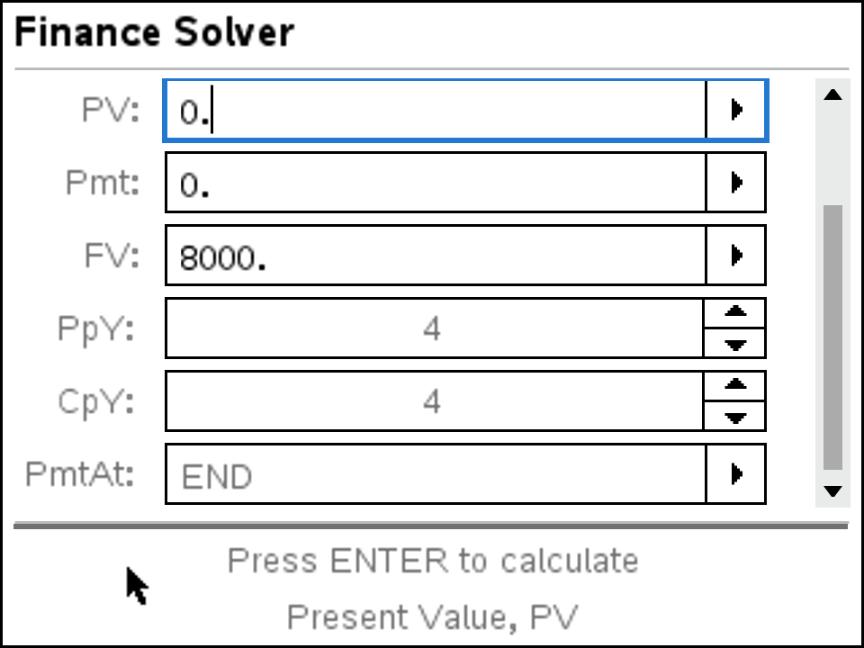
3. Select PV and press Enter
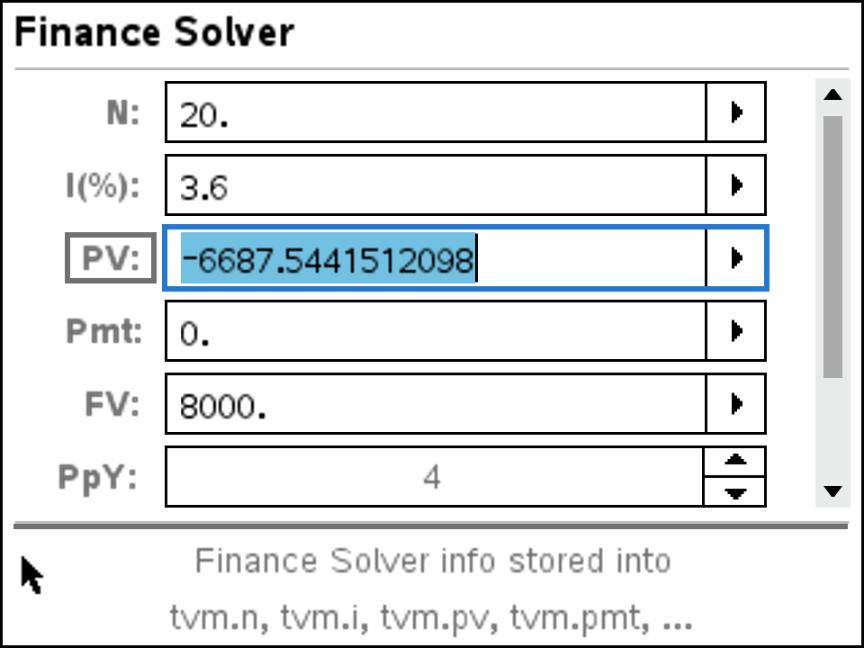
4. Interpret the result
The solver gives \[\mathrm{PV}=-6687.544151\ldots\] The minus sign records money leaving us when we make the deposit.
The amount invested is therefore $6687.54 to the nearest cent.
Read the wording: if asked for the minimum deposit in cents to reach at least $8000, round the unrounded amount up to $6687.55.
Why is the equation’s \(x\) positive but the solver’s PV negative? The equation describes an account balance; the solver records the direction of the cash flow.
Find the nominal annual interest rate | Solve I(%)
Worked example 4 | The unknown is a percentage rate
Question
$6000 grows to $7000 in three years with monthly compounding. Find the nominal annual interest rate to three significant figures.
Solution
Let \(r\%\) be the nominal annual rate. Starting from the compound-interest formula, \[7000=6000\left(1+\frac{r}{100\times12}\right)^{12\times3} =6000\left(1+\frac{r}{1200}\right)^{36}.\]
Booklet: compound interest is given in 1.4; the Finance Solver finds the unknown rate.
TI-Nspire CX | Finance Solver
There are \(12\times3=\textbf{36 months}\). Enter PV = \(-6000\), FV = 7000 and Pmt = 0. Set PpY = CpY = 12, then solve I(%).
| N | I(%) | PV | Pmt | FV | PpY | CpY | PmtAt |
| 36 | solve | -6000 | 0 | 7000 | 12 | 12 | END |
1. Enter the known values
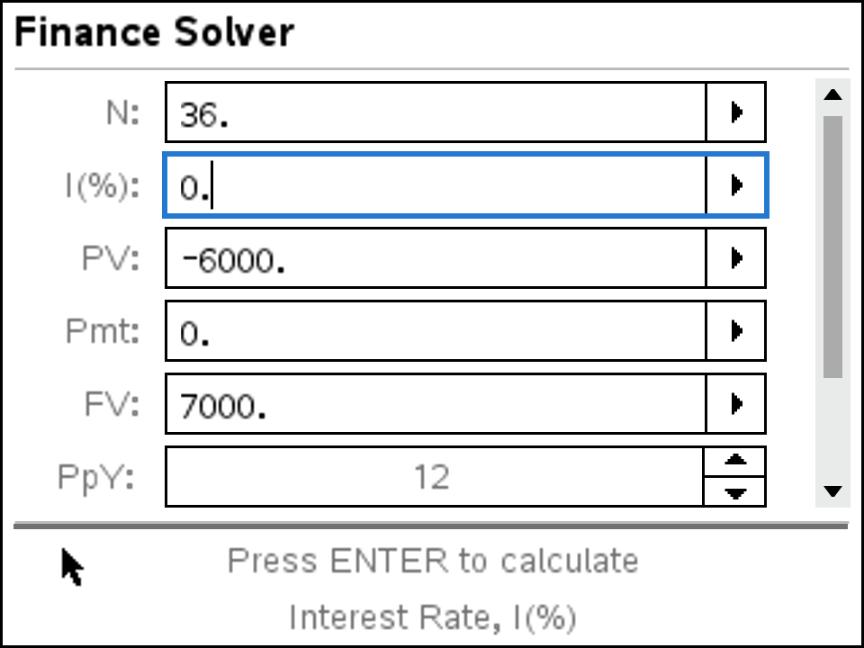
2. Check the lower settings
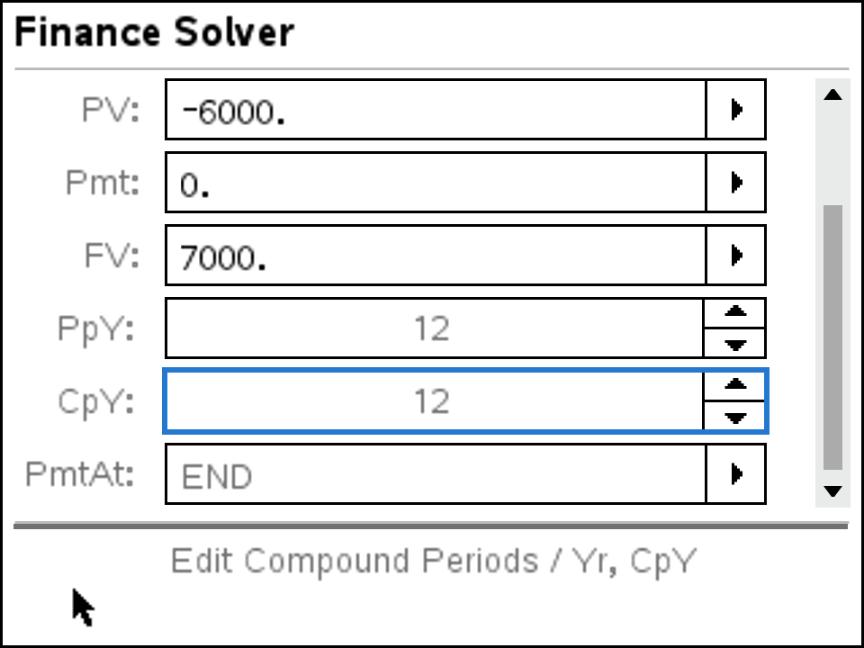
3. Select I(%) and press Enter
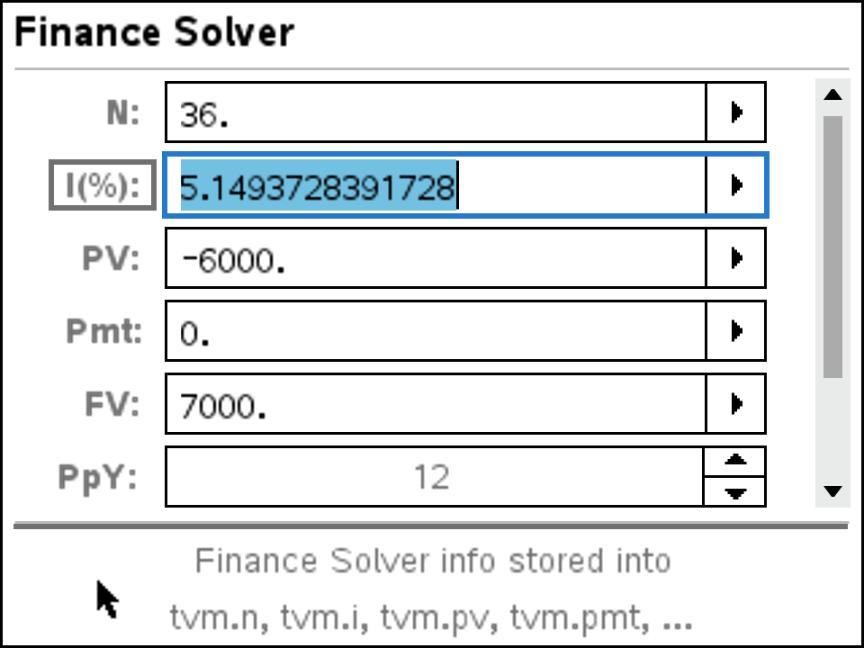
4. Interpret the result
The solver gives \[\mathrm{I}(\%)=5.149372839\ldots\] The nominal annual interest rate is therefore 5.15% to three significant figures.
This output is already an annual percentage. Do not multiply it by 100 or by 12.
Monthly compounding is handled by PpY = CpY = 12.
Same equation, a simpler calculator routine: the Finance Solver finds the rate directly from the financial inputs. Optional graphical and nSolve methods appear in Appendices C–D.
Find the time | Solve N, then count complete periods
Worked example 5 | The first complete month
Question
$6000 earns a nominal annual rate of 4.5%, compounded monthly. Interest is credited at month-end. Find the minimum number of complete months needed to reach at least $8000.
Solution
With \(m\) months, the monthly multiplier is \(1+4.5/1200=1.00375\): \[V(m)=6000(1.00375)^m,\qquad 6000(1.00375)^m\ge8000.\] First solve the boundary equality \(6000(1.00375)^m=8000\).
Booklet: the model uses 1.4; interpreting the inequality and complete months is our step.
TI-Nspire CX | Finance Solver
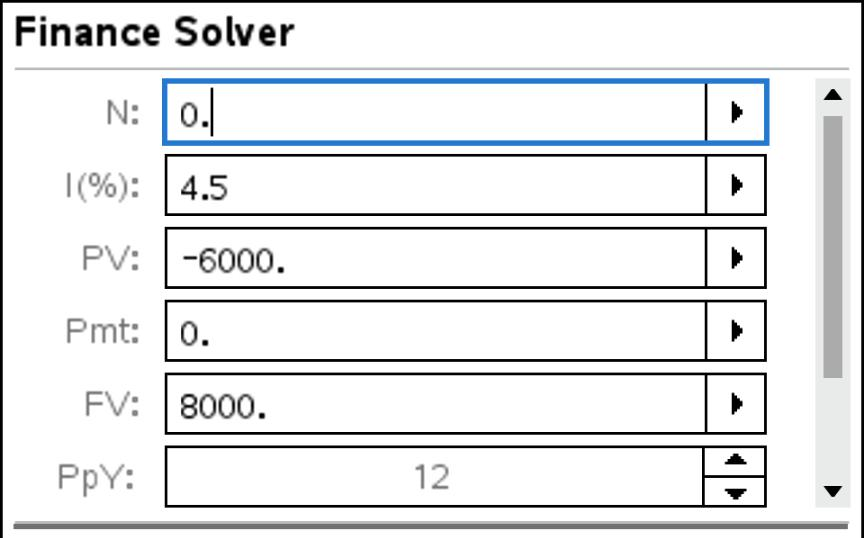
Set PpY = CpY = 12, so N counts months. Enter the known values below, then solve N.
| N | I(%) | PV | Pmt | FV | PpY | CpY | PmtAt |
| solve | 4.5 | -6000 | 0 | 8000 | 12 | 12 | END |
1. Enter the known values
2. Check the lower settings
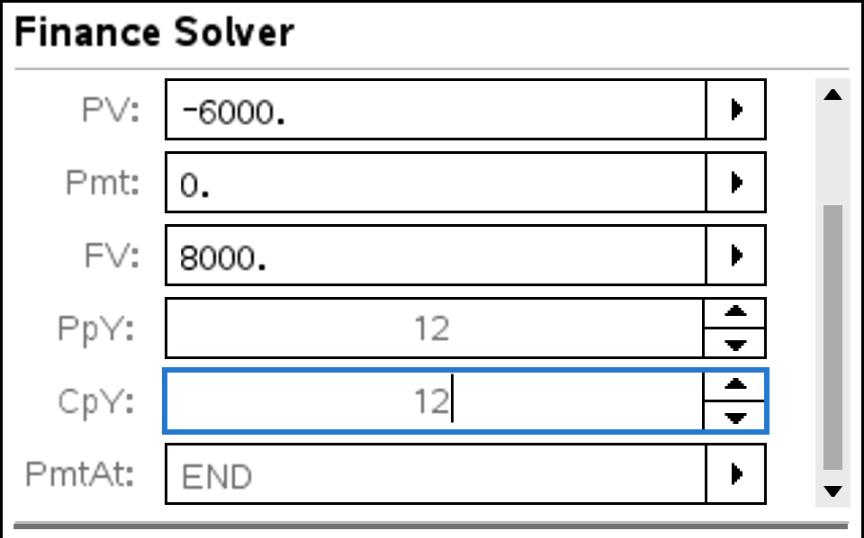
3. Select N and press Enter
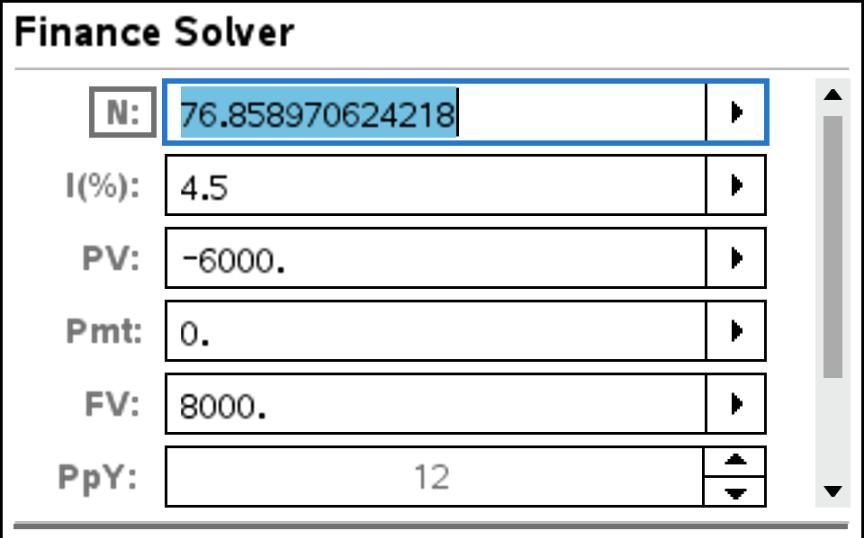
4. Interpret the result
The solver gives \[\mathrm{N}=76.858970624\ldots\] This is a boundary time in months, not years.
Interest is credited only at month-end. The first possible complete month is therefore 77.
We must check months 76 and 77 against the target before concluding.
Check the neighbouring whole months
On a Calculator page, evaluate
6000*1.00375^76
and
6000*1.00375^77
: \[V(76)\approx\$7974.32<\$8000,\qquad V(77)\approx\$8004.22>\$8000.\] The first qualifying month-end is after 77 months, or 6 years and 5 months. For an increasing balance, round a non-integer boundary up to reach the target.
Annual depreciation: model a percentage decrease
Depreciation is a fall in an asset’s value. A 15% annual loss means retaining \(100\%-15\%=85\%\) of the current value each year: multiply by \(0.85\).
The depreciation formula
For initial value \(V_0\) and annual depreciation rate \(p\%\), \[\boxed{V_n=V_0\left(1-\frac{p}{100}\right)^n}.\] Here \(n\) is the number of years. The multiplier \(q=1-p/100\) is less than 1 for \(0<p<100\).
Booklet: not given separately; adapt the geometric formula in 1.3, starting at time zero.
Worked example 6 | A car's value and total loss
Question
A car costs $24000 and depreciates by 15% of its current value each year. Find (a) its value after four years and (b) the total value lost.
Solution
(a) Use \(V_n=V_0(1-p/100)^n\) with \(V_0=24000\), \(p=15\) and \(n=4\): \[V_4=24000\left(1-\frac{15}{100}\right)^4=24000(0.85)^4=\boxed{\$12528.15}.\] On a Calculator page, enter
24000*(1-15/100)^4
(b) Total value lost \(=V_0-V_4\): \[24000-12528.15=\boxed{\$11471.85}.\]
Booklet: total value lost is not given as a separate formula.
| Year | 0 | 1 | 2 | 3 | 4 |
|---|---|---|---|---|---|
| Value ($) | 24000 | 20400 | 17340 | 14739 | 12528.15 |
Each entry is the previous entry multiplied by \(0.85\). The monetary loss gets smaller each year because it is 15% of a smaller value.
A fixed percentage is not a fixed amount
Do not subtract \(4\times15\%=60\%\) of the original price after four years. Each year’s percentage applies to the current value. A fixed monetary loss would instead give an arithmetic model.
Find an unknown depreciation rate
Worked example 7 | Set up a decay equation
Question
A machine falls from $20000 to $14580 in three years. Find its constant annual percentage depreciation.
Solution
Let \(p\%\) be the annual depreciation rate. Use \(V_n=V_0(1-p/100)^n\): \[\boxed{14580=20000\left(1-\frac{p}{100}\right)^3},\qquad 0\le p\le100.\]
Booklet: this depreciation model is adapted from 1.3; it is not a separate booklet formula.
Method 1: nSolve. Let \(x\) represent \(p\) and enter
nSolve(20000*(1-x/100)^3=14580,x,0,100)
The output is \(x=10\). The annual depreciation rate is 10%.
Check: \(20000(1-10/100)^3=20000(0.9)^3=14580\).
Method 2 | Graph the decay equation
Graph \(f_1(x)=20000(1-x/100)^3\) and \(f_2(x)=14580\).
Use \(x_{\min}=0\), \(x_{\max}=30\), \(y_{\min}=5000\), \(y_{\max}=21000\). Find the intersection, using bounds 5 and 15.
The intersection is \((10,14580)\). Here the \(x\)-coordinate represents the annual depreciation percentage, not the number of years.
On the meaningful interval \(0\le x\le100\), increasing the depreciation rate decreases the final value, so there is one solution.
A depreciation percentage and a signed growth rate differ
In our formula \(1-p/100\), a loss of 10% means \(p=10\). In the Finance Solver, I(%) would be \(-10\), with annual settings. Both describe the same decrease; read the meaning of the variable before interpreting its sign.
Inflation: prices, nominal value and real value
Inflation is an increase in general prices. The nominal value is the account balance; the real value is its buying power in today’s money.
Prices also grow geometrically
At annual inflation \(h\%\), a price \(C_0\) becomes \(C_n=C_0(1+h/100)^n\) after \(n\) years.
Booklet: not given separately; adapt the geometric model in 1.3.
Example. At 2.5% inflation, a $100 basket costs \(100(1.025)^5\approx\$113.14\) after five years. Prices have multiplied by \(1.025^5\). Divide by this factor to return to today’s buying power.
Real value: undo the price growth
\[\boxed{\text{real value}=\frac{\mathrm{FV}}{(1+h/100)^n}}.\]
Booklet: not given; divide the nominal balance by the price multiplier over the same years.
Worked example 8 | Balance growth versus buying power
Question
$10000 earns 4% per year, compounded annually, for five years. Inflation is 2.5% per year. Give money to the nearest cent. Find:
the nominal final balance;
its real value in today’s money;
the gain in buying power;
the real annual rate (the annual percentage growth in buying power), to three significant figures. Use the unrounded rate to check part (b).
Solution
(a) Grow the investment using compound interest: \[\mathrm{FV}=10000\left(1+\frac{4}{100}\right)^5=12166.529024\approx\boxed{\$12166.53}.\] (b) Divide by the price multiplier: \[\text{real value}=\frac{10000(1.04)^5}{(1.025)^5}=10753.438843\ldots\approx\boxed{\$10753.44}.\] (c) Gain in buying power \(=10753.438843\ldots-10000\approx\boxed{\$753.44}\).
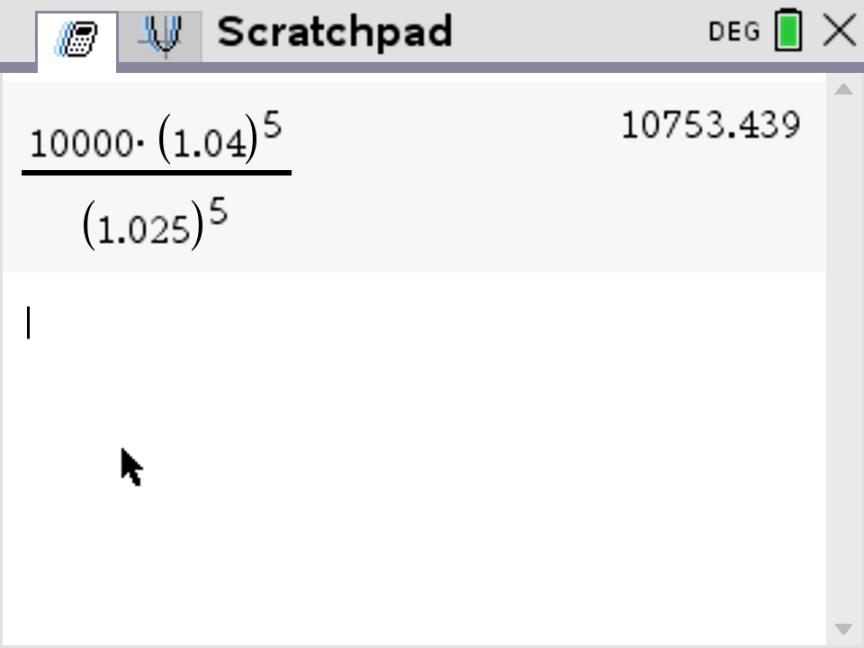
TI-Nspire CX | Scratchpad
Enter
(10000*1.04^5)/1.025^5
This avoids rounding the nominal balance first. The displayed \(10753.439\) gives $10753.44 to the nearest cent.
Inflation divides; depreciation multiplies
Undo 2.5% annual inflation by dividing by \(1.025^n\), not multiplying by \(0.975^n\). With monthly interest over five years, compound interest uses 60 months, but annual inflation still uses an exponent of 5 years.
Worked example 8 | Continued: a real annual rate
Solution
(d) How much does buying power grow in one year?
Step 1: start with $100 to make the percentage clear. After one year, 4% interest gives \(100\times1.04=\$104\). Prices have multiplied by \(1.025\), so its value in today’s money is \[104\div1.025=101.463414634\ldots.\] Step 2: express the gain as a percentage of the original $100. \[\frac{101.463414634\ldots-100}{100}\times100\% =1.463414634\ldots\%\approx\boxed{1.46\%}.\] This is the real annual rate: buying power grows by about 1.46% each year. In Scratchpad, enter
((104/1.025-100)/100)*100
Keep the unrounded result for the next step.
Booklet: this real-rate calculation is not given separately. Use the percentage-change calculation; no additional general formula is needed here.
Step 3: use the annual growth to check part (b). A gain of \(1.463414634\ldots\%\) means multiplying each year by \[1+\frac{1.463414634\ldots}{100} =1.014634146\ldots=\frac{1.04}{1.025}.\] Apply this multiplier five times to the original $10000: \[\text{real value}=10000\left(\frac{1.04}{1.025}\right)^5 =10753.438843\ldots\approx\boxed{\$10753.44}.\] In Scratchpad, enter
10000*(1.04/1.025)^5
This gives the same answer as part (b): dividing by the inflation multiplier each year is equivalent to dividing by the five-year inflation multiplier at the end.
The equivalent investment with no inflation
Earning 4% with 2.5% inflation gives the same growth in buying power as earning \(1.463414634\ldots\%\) with no inflation.
| After five years | Actual investment | No-inflation model |
|---|---|---|
| Money in the account | $12166.53 | $10753.44 |
| Buying power in today’s money | $10753.44 | $10753.44 |
The actual account still earns 4%. Since interest compounds annually, its effective annual interest rate is 4%. The \(1.463414634\ldots\%\) is the real annual rate, after allowing for inflation.
Keep the exact multiplier
Use \(1.04/1.025\) in later calculations. Rounding the rate to 1.46% too early changes the final cents. Also, \(4\%-2.5\%=1.5\%\) is only an approximation to the real rate.
AI SL syllabus focus. SL 1.4 includes finding an investment’s real value from its interest and inflation rates, using technology where appropriate. Part (d) is a guided alternative calculation within that context; the real annual rate is not a separately named syllabus item. The compound-interest formula is supplied in the booklet; deriving it is not an examination requirement.
Compare accounts: effective annual growth
The nominal annual rate is the quoted rate before allowing for compounding within a year. To compare accounts, use the same initial deposit and time.
Worked example 9 | Understand the effective rate first
Question
$5000 is invested for three years. A pays 4.85% per year, compounded annually. B pays a nominal annual rate of 4.8%, compounded monthly.
Find each balance after one year and its percentage gain. Which grows faster?
Find both three-year balances and their difference.
Solution
(a) Use the compound-interest formula for one year: \[\mathrm{FV}_A=5000(1.0485)=5242.50,\quad \mathrm{FV}_B=5000\left(1+\frac{4.8}{1200}\right)^{12}=5245.351037\ldots\] Percentage gain \(=(\text{final}-\text{initial})/\text{initial}\times100\%\): \[A:\ \frac{5242.50-5000}{5000}\times100\%=4.85\%,\qquad B:\ \frac{5245.351037\ldots-5000}{5000}\times100\%\approx4.90702\%.\] These actual one-year percentage gains are the effective annual rates. B grows faster despite its lower quoted rate.
(b) After three years, \(5000(1.0485)^3\approx\$5763.35\) and \(5000(1.004)^{36}\approx\$5772.76\). Using unrounded balances, B gives $9.41 more.
From the example to the formula
B’s one-year multiplier is \(1.004^{12}\). Subtract 1 to isolate the gain, then multiply by 100 to express it as a percentage. In general, \[\boxed{\text{effective annual rate}=100\left[\left(1+\frac{r}{100k}\right)^k-1\right]\%}.\]
Booklet: not given separately; it follows from compound interest over one year.
Apply to B: \(100[(1+4.8/1200)^{12}-1]\%=4.907020753\ldots\%\), agreeing with the example. This shortcut performs the same steps in one calculation.
Compare before rounding. Close rates can round to the same value. Compare annual inflation with effective annual growth to judge whether buying power increases.
Practice | Build calculator confidence
Use a calculator. Give money to the nearest cent and rates to three significant figures unless stated. Write the formula and substitute the data before calculating. For Finance Solver solutions, record the inputs and identify the field solved. Assume no further transactions, fees or taxes.
Simple or compound? $2500 is invested for three years at 4% per year.
For simple interest, find the interest added each year and the final value.
For annual compound interest, find the final balance by entering the compound-interest expression directly.
How much more interest is earned with compound interest?
Monthly compounding. $4200 is invested for 2.5 years at a nominal annual rate of 6%, compounded monthly.
Write the compound-interest expression, including the correct exponent.
Find the final balance and total interest earned.
Give the corresponding Finance Solver inputs and identify the unknown.
Work backwards. An account pays a nominal annual rate of 3.2%, compounded quarterly. Use the Finance Solver to find the initial deposit that grows to $9000 in four years, to the nearest cent. Explain the sign of the calculator’s PV.
Unknown interest rate. $4500 grows to $5400 in four years with annual compounding. Write an equation for the annual percentage rate, then solve for I(%) with the Finance Solver.
A whole-year target. $3000 earns 5.5% per year, compounded annually, with interest credited at year-end.
Write the boundary equation for a target of $4000; solve for N with the Finance Solver.
Find the first complete year-end when the balance is at least $4000. Check the balances on either side of the boundary.
Depreciating laptop. A laptop initially worth $1800 loses 18% of its current value each year. Find (a) its value after three years and (b) the total loss in value.
Unknown depreciation rate. A machine falls from $16000 to $10125 in four years. Use nSolve to find the constant annual depreciation rate. Explain why a Finance Solver check would instead give a negative I(%).
Choose a method that fits the question
Evaluate known expressions directly. For standard compound-interest questions, use the Finance Solver to find PV, FV, I(%) or N. The depreciation methods remain as taught; optional alternatives for investment questions appear in Appendices A–E.
Practice | Compare, interpret and combine
Compare two accounts. $7000 is invested for three years. A pays 4.7% per year, compounded annually. B pays a nominal annual rate of 4.6%, compounded monthly.
Find each final balance, keeping unrounded values for comparison.
Which account gives the greater final balance, and by how much?
Find B’s effective annual rate using a one-year calculation. Explain why you must compare before rounding.
Allow for inflation. $8000 earns 3.5% per year, compounded annually, for four years. Inflation is 2.2% per year.
Find the nominal final balance.
Find its real value in today’s money and the gain in buying power.
Explain why a larger account balance does not always mean greater buying power.
First complete month. $9000 earns a nominal annual rate of 4.2%, compounded monthly. Interest is credited at each month-end. The target balance is $10500.
Write a boundary equation and use the Finance Solver to find N. State the time unit.
Find the minimum number of complete months needed. Explain your rounding and check the neighbouring balances.
A rate changes. $12000 earns 3% per year for two years, then 4.2% per year for the next three years. Interest is compounded annually throughout. Inflation stays at 2.5% per year.
Find the balance after two years, then use it as the starting amount for the next three years. Find the final balance.
Find the final balance’s real value in today’s money.
Explain why one constant-ratio geometric sequence does not describe all five years.
Explain the mistake. Correct each statement.
“PV = \(-6000\) means that I have lost $6000.”
“At 4.2% compounded monthly, I should enter I(%) = 0.35.”
“An initial deposit of $6000 means that I should enter Pmt = 6000.”
“A solver result of N = 44.12 means 44 months is enough to reach the target.”
“My $6000 earns 2% per year while inflation is 3%, so I am better off after four years because the balance is larger.” Support your correction with calculations, assuming annual compounding.
Answers | Models and core skills
The equations below show the model before calculation. Equivalent correct calculator methods are acceptable unless a question specifies one.
1. Simple or compound?
(a) Annual simple interest \(=2500(0.04)=\$100\). Final value \(=2500[1+3(4)/100]=\$2800.00\).
(b) Compound interest: \(\mathrm{FV}=2500(1.04)^3=\$2812.16\).
(c) Extra interest \(=2812.16-2800=\textbf{\$12.16}\).
2. Monthly compounding
(a) \(\mathrm{FV}=4200(1+6/1200)^{12(2.5)}=4200(1.005)^{30}\).
(b) \(\mathrm{FV}=4877.880348\ldots\approx\textbf{\$4877.88}\). Interest earned \(=4877.880348\ldots-4200\approx\textbf{\$677.88}\).
(c) Finance Solver: N = 30, I(%) = 6, PV = \(-4200\), Pmt = 0, PpY = CpY = 12, END; solve FV.
3. Required initial deposit
Let \(x\) be the deposit. \(9000=x(1+3.2/400)^{16}\).
Finance Solver: N = 16, I(%) = 3.2, Pmt = 0, FV = 9000, PpY = CpY = 4, END. Solve PV to obtain \(-7922.714309\ldots\). Deposit $7922.71 to the nearest cent. PV is negative because money leaves us; the amount deposited is positive.
4. Unknown annual interest rate
Let \(r\%\) be the rate. \(5400=4500(1+r/100)^4\).
Finance Solver: N = 4, PV = \(-4500\), Pmt = 0, FV = 5400, PpY = CpY = 1, END. Solve I(%) to obtain \(4.663513939\ldots\). The annual rate is 4.66% (3 s.f.).
5. A whole-year target
(a) Solve \(3000(1.055)^n=4000\). Finance Solver: I(%) = 5.5, PV = \(-3000\), Pmt = 0, FV = 4000, PpY = CpY = 1, END. Solve N to obtain \(5.373140673\ldots\) years.
(b) First qualifying year-end: 6 years. Check \(3000(1.055)^5\approx\$3920.88<\$4000\) and \(3000(1.055)^6\approx\$4136.53>\$4000\).
6. Depreciating laptop
(a) \(V_3=1800(1-18/100)^3=992.4624\approx\textbf{\$992.46}\).
(b) Total loss \(=1800-992.4624\approx\textbf{\$807.54}\).
7. Unknown depreciation rate
Let \(p\%\) be the depreciation rate. \(10125=16000(1-p/100)^4\).
nSolve(16000*(1-x/100)^4=10125,x,0,100)
gives \(p=10.809466\ldots\). Annual depreciation: 10.8%. The Finance Solver instead returns I(%) \(=-10.809466\ldots\), a signed decrease.
Answers | Compare, interpret and combine
8. Compare two accounts
(a) \(\mathrm{FV}_A=7000(1.047)^3=8034.115761\approx\textbf{\$8034.12}\);
\(\mathrm{FV}_B=7000(1+4.6/1200)^{36}=8033.709071\ldots\approx\textbf{\$8033.71}\).
(b) Using unrounded values, A gives $0.41 more.
(c) B’s one-year multiplier is \((1+4.6/1200)^{12}\). Its effective annual rate is \(100[(1+4.6/1200)^{12}-1]\%=4.698233\ldots\%\). This rounds to 4.70% (3 s.f.), but is slightly below A’s 4.7%. Compare before rounding.
9. Allow for inflation
(a) \(\mathrm{FV}=8000(1.035)^4=9180.184005\approx\textbf{\$9180.18}\).
(b) Real value \(=8000(1.035)^4/(1.022)^4\approx\textbf{\$8414.88}\).
Gain in buying power \(=8414.877594\ldots-8000\approx\textbf{\$414.88}\).
(c) Prices may increase faster than savings, so a larger nominal balance can buy less than the original deposit could buy.
10. First complete month
(a) Let \(m\) count months. The boundary equation is \(9000(1+4.2/1200)^m=10500\). Finance Solver: I(%) = 4.2, PV = \(-9000\), Pmt = 0, FV = 10500, PpY = CpY = 12, END. Solve N to obtain \(44.12008184\ldots\) months.
(b) Round up to 45 months. Check \(V(44)\approx\$10495.60\) and \(V(45)\approx\$10532.33\). Only month 45 reaches the target.
11. A rate changes
(a) After two years: \(12000(1.03)^2=\textbf{\$12730.80}\). Then apply three years of growth at 4.2%: \[\mathrm{FV}=12000(1.03)^2(1.042)^3=14403.195393\ldots\approx\boxed{\$14403.20}.\] (b) Real value \(=12000(1.03)^2(1.042)^3/(1.025)^5\approx\textbf{\$12730.33}\).
(c) The annual multiplier changes from 1.03 to 1.042, so there is no single constant common ratio throughout the five years.
12. Explain the mistake
(a) Negative PV records money leaving us, not a loss.
(b) Enter I(%) = 4.2, with PpY = CpY = 12. The solver uses the annual percentage rate.
(c) The single initial deposit belongs in PV = \(-6000\). Set Pmt = 0 because there are no regular payments into or out of the account.
(d) An increasing balance reaches this boundary after 44.12 months; the first qualifying whole month-end is month 45.
(e) Nominal balance \(=6000(1.02)^4\approx\$6494.59\). Real value \(=6000(1.02)^4/(1.03)^4\approx\$5770.36\). Buying power has fallen by $229.64.
Quick reference | Formulas and calculator methods
The models at a glance
Use \(n\) in years; \(r\%\) is the nominal annual interest rate, \(k\) the number of compounding periods per year, \(p\%\) annual depreciation and \(h\%\) annual inflation.
| Model | Formula | In the booklet? |
|---|---|---|
| Simple interest | \(u_n=u_0(1+nr/100)\); equivalently\(\mathrm{FV}=\mathrm{PV}(1+nr/100)\) | Not separately |
| Geometric growth | \(u_n=u_0q^n\) | Adapted from 1.3 |
| Compound interest | \(\mathrm{FV}=\mathrm{PV}(1+r/(100k))^{kn}\) | Yes: 1.4 |
| Annual depreciation | \(V_n=V_0(1-p/100)^n\) | Not separately |
| Price inflation | \(C_n=C_0(1+h/100)^n\) | Not separately |
| Real value | \(\displaystyle\frac{\mathrm{FV}}{(1+h/100)^n}\) | No |
| Effective annual rate | \(\displaystyle100\left[(1+r/(100k))^k-1\right]\%\) | No |
Interest earned \(=\mathrm{FV}-\mathrm{PV}\); value lost \(=V_0-V_n\). These are not separate booklet formulas. In these balance formulas, the initial and final amounts are positive.
Set up the mathematics, then use the appropriate calculator tool
Define the unknown and its units. Is it money, an annual percentage, years or months?
Write the formula and substitute. Keep the unknown visible in the equation.
Calculate or solve.
All quantities known: enter the expression directly.
Standard compound interest: use the Finance Solver. Set Pmt = 0 and PpY = CpY = \(k\); solve PV, FV, I(%) or N. N counts compounding periods, and I(%) is the nominal annual rate.
For other equations, use the numerical or graphical methods shown in the lesson. Optional investment alternatives are in Appendices A–E.
Interpret and check. Include units, use the requested accuracy, and verify whole-period conditions using neighbouring values.
Four checks that prevent common errors
Units: monthly compounding uses \(12n\) periods, but annual inflation uses \(n\) years.
Solutions: nSolve finds one at a time; check the meaningful domain.
Precision: keep unrounded results for comparisons and later calculations.
Signs: positive balances in formulas; signed cash flows in the Finance Solver.
Optional alternative | Find a deposit with nSolve
The Finance Solver is our main method for standard compound-interest questions. The optional methods in Appendices A–E solve the same equations in other ways.
Worked example 3 revisited | An optional nSolve solution
Question
An investment must grow to $8000 in five years. The nominal annual rate is 3.6%, compounded quarterly. Find the initial deposit to the nearest cent.
Solution
Let \(x\) be the initial deposit, in dollars. Use \(\mathrm{FV}=\mathrm{PV}(1+r/(100k))^{kn}\) with \(r=3.6\), \(k=4\) and \(n=5\): \[\boxed{x\left(1+\frac{3.6}{100\times4}\right)^{4\times5}=8000}, \qquad\text{or}\qquad x(1.009)^{20}=8000.\]
Booklet: the compound-interest formula is given in 1.4; this is its substitution for this question.
TI-Nspire CX | Numerical Solve
Open a Calculator page or the calculator in Scratchpad. Use a variable such as \(x\) that has no stored value.
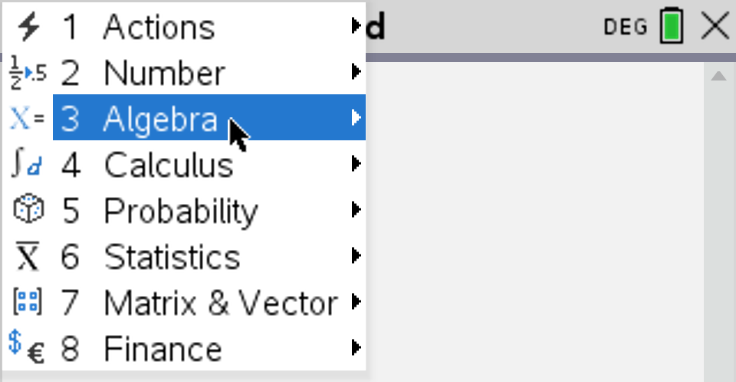
1. Menu \(\to\) Algebra
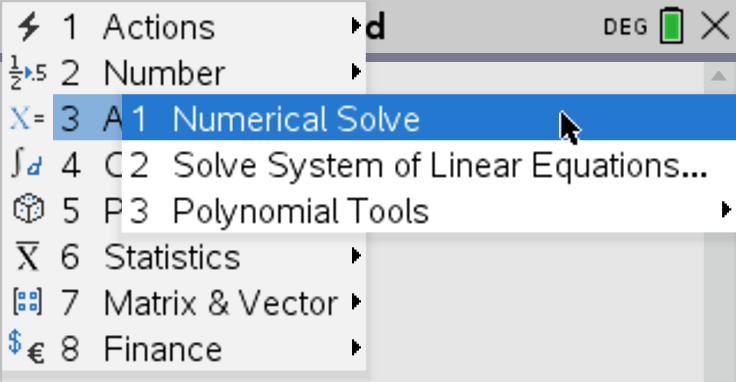
2. Choose Numerical Solve
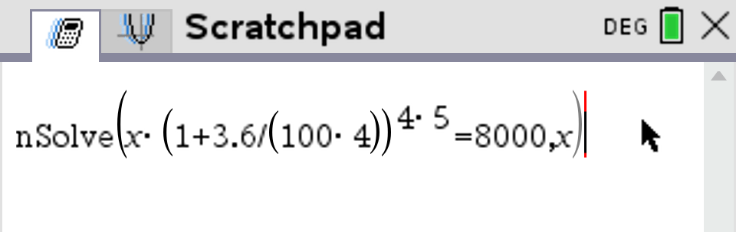
Enter the equation, a comma, then the unknown \(x\):
nSolve(x*(1+3.6/(100*4))^(4*5)=8000,x)
3. Check the complete entry
4. Press Enter for the result
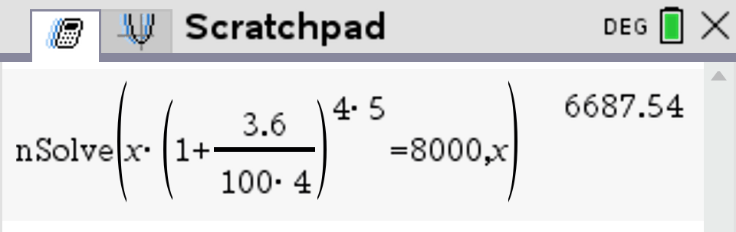
The calculator displays \(6687.54\). The unrounded solution is \(x=6687.544151\ldots\), so the required deposit is $6687.54 to the nearest cent. Here \(x\) is a positive deposit, not the Finance Solver’s signed PV.
nSolve returns one solution at a time
Here increasing \(x\) increases the final balance, so there is exactly one positive deposit. When an equation may have several solutions, a single nSolve result is not a complete answer: inspect the graphs and find the relevant intersections.
To restrict the search, use
nSolve(equation,x,lower,upper)
; adding
,0,8000
after \(x\) searches from 0 to 8000.
Interpret rounding: for the minimum deposit in cents to reach at least $8000, use the unrounded result and round up to $6687.55.
Optional alternative | Find a deposit graphically
Worked example 3 revisited | A graphical solution
Question
An investment must grow to $8000 in five years at a nominal annual rate of 3.6%, compounded quarterly. Find the initial deposit to the nearest cent.
Solution
Turn the equation into an intersection problem. Let \(x\) be the initial deposit. We need \(x(1.009)^{20}=8000\). Graph the left and right sides as two functions: \[f_1(x)=x(1.009)^{20},\qquad f_2(x)=8000.\] At their intersection, the two outputs are equal. The \(x\)-coordinate is the required initial deposit; the \(y\)-coordinate is the final balance of $8000.
TI-Nspire CX | Graph intersection, step by step
Add a Graphs page. After the \(f_1(x)=\) prompt, enter
x*(1+3.6/(100*4))^(4*5)and press Enter. Then enter
8000after \(f_2(x)=\). These are the two functions above.
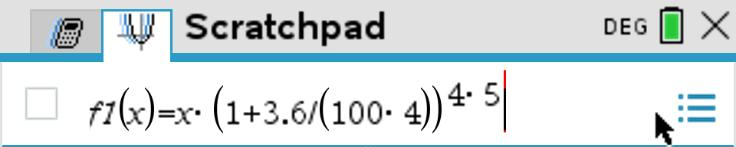
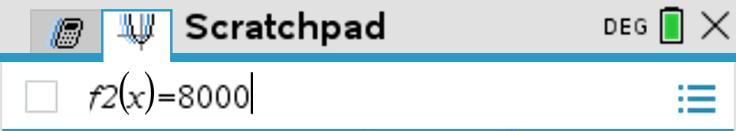
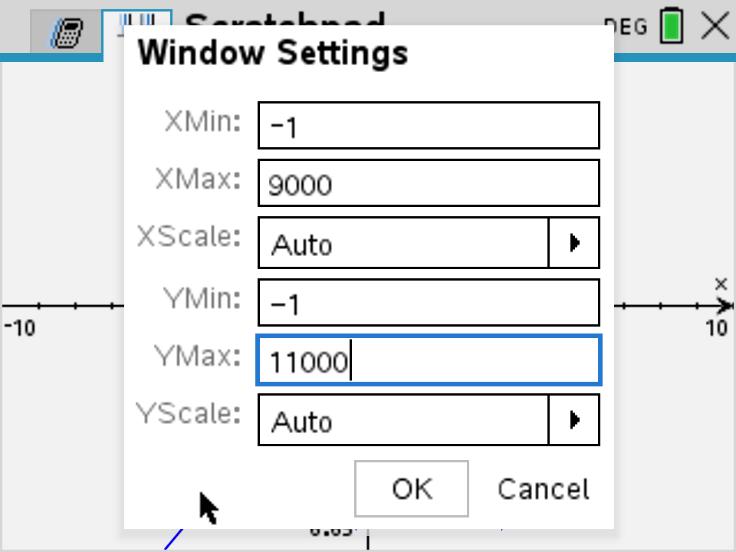
Choose Menu \(\to\) Window/Zoom \(\to\) Window Settings. Match the capture below: \(x_{\min}=-1\), \(x_{\max}=9000\), \(y_{\min}=-1\), \(y_{\max}=11000\); leave both scales on Auto.
Choose Menu \(\to\) Analyze Graph \(\to\) Intersection. If prompted, select the two graphs. Select a lower bound to the left of the crossing, then an upper bound to its right; for example \(x=6000\) and \(x=7500\).
Set a suitable viewing window
Find the intersection
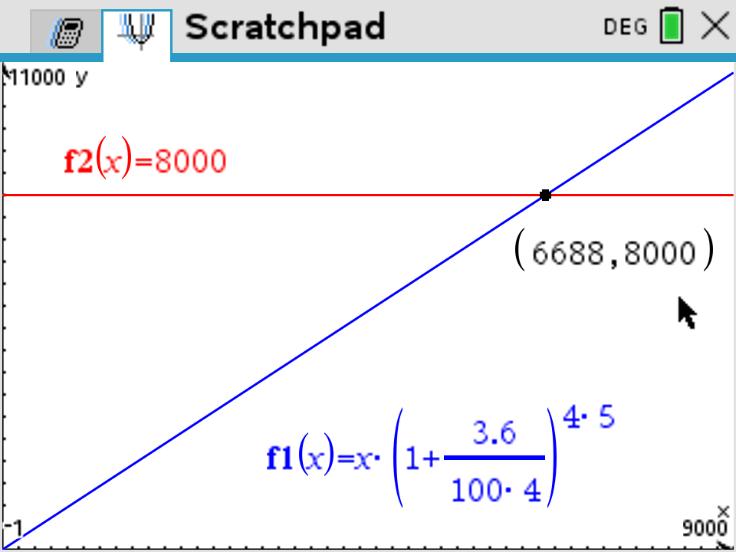
Use enough digits before rounding
Read the \(x\)-coordinate: the capture displays \((6688,8000)\), with rounded coordinates. For a nearest-cent answer, increase the displayed precision or use nSolve, as on the previous page: \(x=6687.544151\ldots\). The required deposit is $6687.54. Both methods solve the same equation.
The standard \(-10\) to \(10\) window cannot show a final balance of $8000. Use a suitable window, then Intersection; do not estimate the crossing from pixels.
Another valid approach: graph \(y=x(1.009)^{20}-8000\) and find its zero with Analyze Graph \(\to\) Zero. Its \(x\)-intercept gives the same deposit.
Optional alternative | Find the rate graphically
Worked example 4 revisited | A graphical solution
Question
$6000 grows to $7000 in three years with monthly compounding. Find the nominal annual interest rate to three significant figures.
Solution
Let \(r\%\) be the nominal annual rate. Starting from the booklet’s compound-interest formula, \[7000=6000\left(1+\frac{r}{100\times12}\right)^{12\times3} =6000\left(1+\frac{r}{1200}\right)^{36}.\]
Booklet: compound interest is given in 1.4; we solve the substituted equation graphically.
TI-Nspire CX | Find the intersection
Use \(x\) on the calculator to represent the percentage \(r\). Graph the two sides of the equation: \[f_1(x)=6000(1+x/1200)^{36},\qquad f_2(x)=7000.\]
Add a Graphs page. After \(f_1(x)=\), enter
6000*(1+x/(100*12))^(12*3)and press Enter. Then enter
7000after \(f_2(x)=\).
Choose Menu \(\to\) Window/Zoom \(\to\) Window Settings. Use a window showing both graphs and their crossing; for example \(0\le x\le15\) and \(0\le y\le12000\).
Choose Menu \(\to\) Analyze Graph \(\to\) Intersection. If prompted, select the two graphs. Choose a lower bound to the left of the crossing and an upper bound to its right, such as \(x=4\) and \(x=6\).
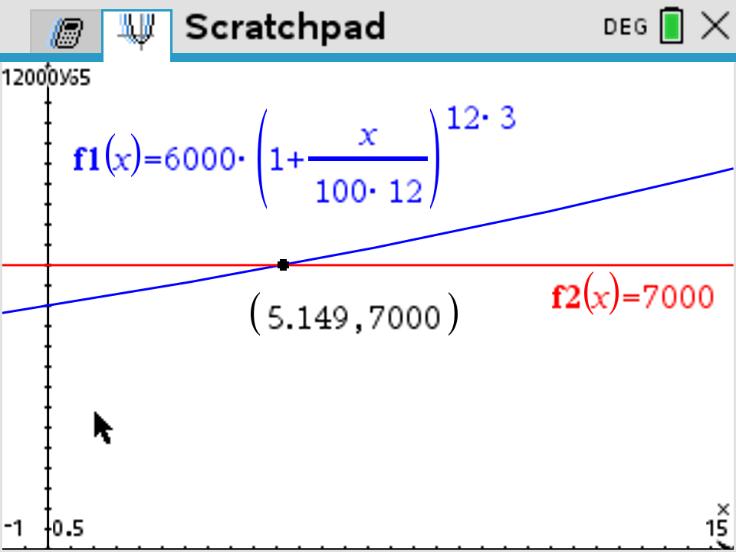
The calculator displays the intersection as \((5.149,7000)\). The \(x\)-coordinate gives the annual percentage rate; the \(y\)-coordinate is the final balance of $7000. Thus \[r\approx5.149\quad\Longrightarrow\quad\boxed{\text{nominal annual interest rate}=5.15\%\text{ (3 s.f.)}}.\]
Know what your variable represents
We wrote \(1+r/1200\), so \(r\) is already an annual percentage. Do not multiply the answer by 100 or 12. If you had chosen a decimal monthly rate instead, its interpretation would be different.
Finance Solver check: N = 36, PV = \(-6000\), Pmt = 0, FV = 7000, PpY = CpY = 12, END. Solve I(%) to get the same rate.
Optional alternative | When nSolve needs help
Worked example 4 revisited | Give nSolve a starting point
Question
$6000 grows to $7000 in three years with monthly compounding. Find the nominal annual interest rate to three significant figures.
Solution
As on the previous page, let \(x\) represent the annual percentage rate. Substituting into the compound-interest formula gives \[6000(1+x/1200)^{36}=7000.\]
1. A correct equation can still give an unsuccessful search
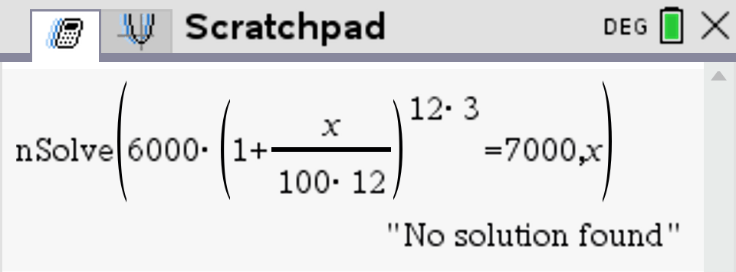
With only the equation and \(x\), this attempt returns “No solution found”.
nSolve searches numerically. This message means that its search did not find a solution; it does not prove that no solution exists. Our graph already shows the intersection.
2. Add an initial guess and lower and upper bounds
The successful entry in the screenshots is:
nSolve(6000*(1+x/(100*12))^36=7000,x=3,0,10)
x=3: start the search near 3%. This is a guess, not the answer.
0: use 0% as the lower bound for the rate.
10: use 10% as the upper bound for the rate.
Successful calculation: left view
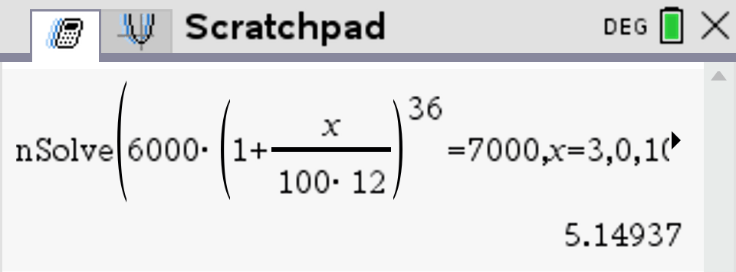
Scroll right to see the bounds
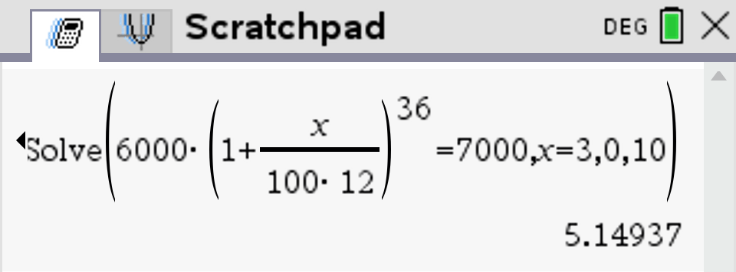
These are two views of the same successful calculation. The displayed result is \(x=5.14937\), giving an annual rate of 5.15% to three significant figures, as found graphically.
Why are 0 and 10 suitable bounds here?
At 0%, the final balance is $6000; at 10%, it is \(6000(1+10/1200)^{36}\approx\$8089.09\). As the rate increases, the final balance increases. The rate producing $7000 therefore lies between 0% and 10%.
When to choose the graphical method
Use the Finance Solver first for standard compound-interest questions. When choosing between these optional equation-solving methods, prefer graphs if you are not comfortable choosing an initial guess and bounds. Plot the two sides and use Intersection, as on the previous page. An unsuccessful nSolve search does not prove that no solution exists.
Optional alternatives | Find the time
Worked example 5 revisited | nSolve and graphical methods
Question
$6000 earns a nominal annual rate of 4.5%, compounded monthly. Interest is credited at month-end. Find the minimum number of complete months needed to reach at least $8000.
Solution
If \(m\) counts months, then \(n=m/12\) years and \(kn=12(m/12)=m\). The monthly multiplier is \(1+4.5/1200=1.00375\). Hence \[V(m)=6000(1.00375)^m,\qquad 6000(1.00375)^m\ge8000.\] First solve the boundary equality \(6000(1.00375)^m=8000\).
Booklet: the model uses 1.4; changing the time unit and interpreting the inequality are our steps.
nSolve: let \(x\) represent months and enter
nSolve(6000*(1+4.5/1200)^x=8000,x,0,100)
This gives \(x=76.858970624\ldots\) months.
Graphical alternative | Find the boundary crossing
Graph \(f_1(x)=6000(1.00375)^x\) and \(f_2(x)=8000\). Use \(0\le x\le100\) and \(5000\le y\le9500\). Find the intersection with bounds 70 and 85.
The \(x\)-coordinate is again \(76.858970624\ldots\). The smooth curve extends the model between month-ends; the question asks for whole month-ends.
Check the neighbouring whole months
On a Calculator page, evaluate the model at \(m=76\) and \(m=77\): \[V(76)\approx\$7974.32<\$8000,\qquad V(77)\approx\$8004.22>\$8000.\] The first qualifying month-end is after 77 months, or 6 years and 5 months. For an increasing balance, round a non-integer boundary up to reach the target.
Do not round the time before interpreting it. A calculator approximation close to a whole number should be checked against the original condition.
Extra Finance Solver practice | Monthly example
Worked example 2 revisited | The Finance Solver
Question
$5000 is invested for three years at a nominal annual rate of 4.8%, compounded monthly. Find (a) the final balance and (b) the total interest earned, to the nearest cent.
Solution
We need FV. Three years gives \(\mathrm{N}=12\times3=36\) months.
1. Enter the known values
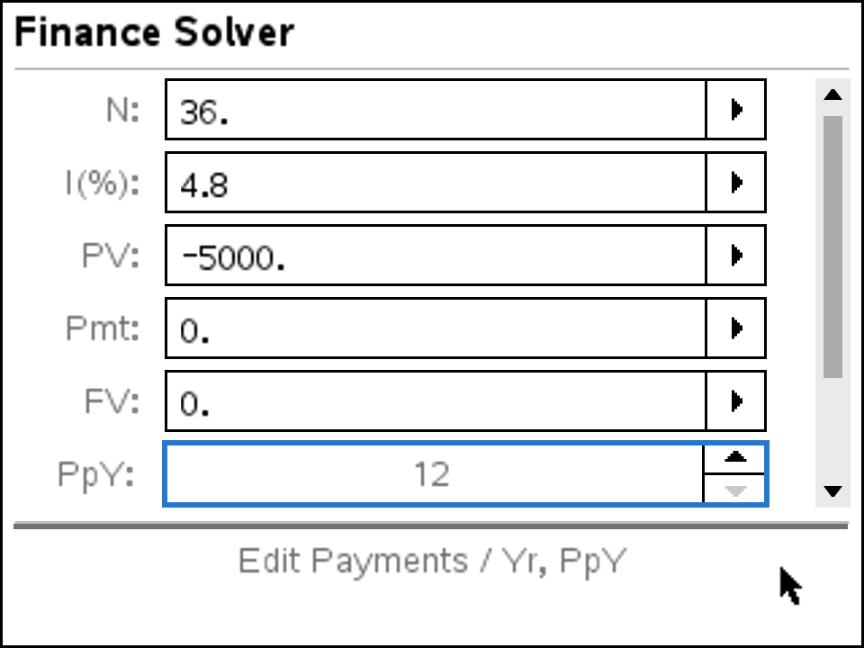
N = 36; I(%) = 4.8; PV = \(-5000\); Pmt = 0; PpY = 12. The displayed FV = 0 has not yet been solved.
2. Check the lower settings
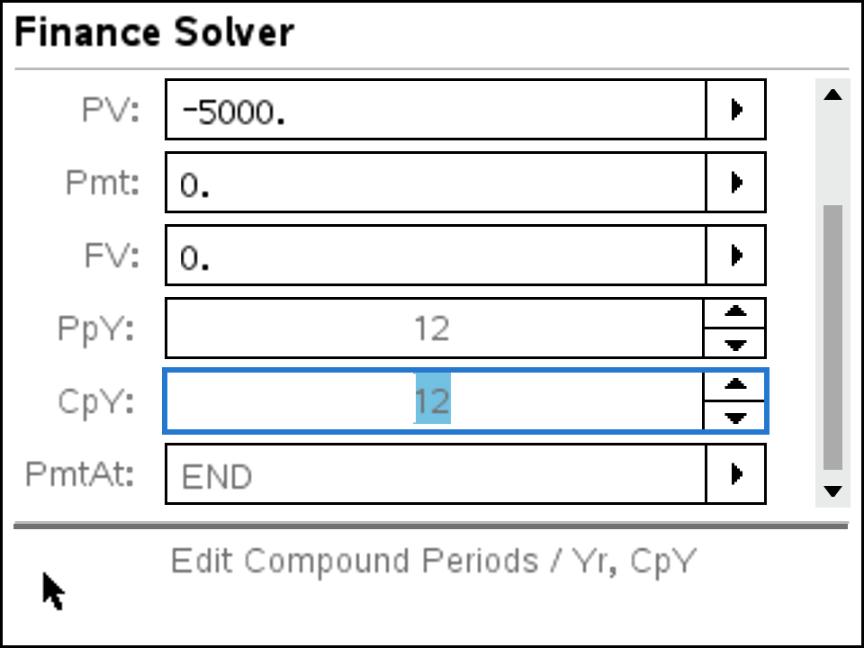
Set CpY = 12 and check PpY = 12. Leave PmtAt at END. N now counts months.
3. Select FV and press Enter
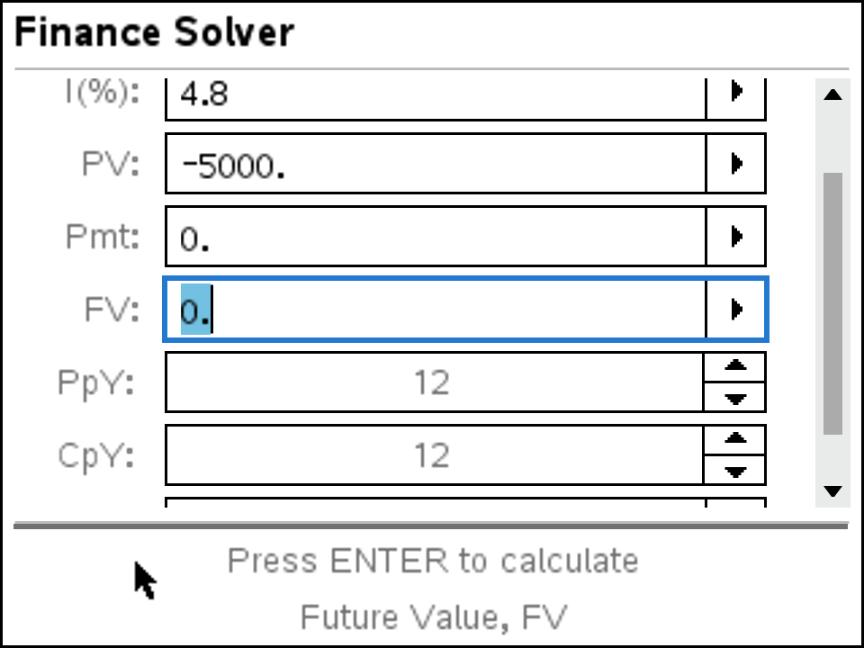
Place the cursor inside the FV cell. Its selected 0 is a starting value, not the answer.
4. Interpret the answer
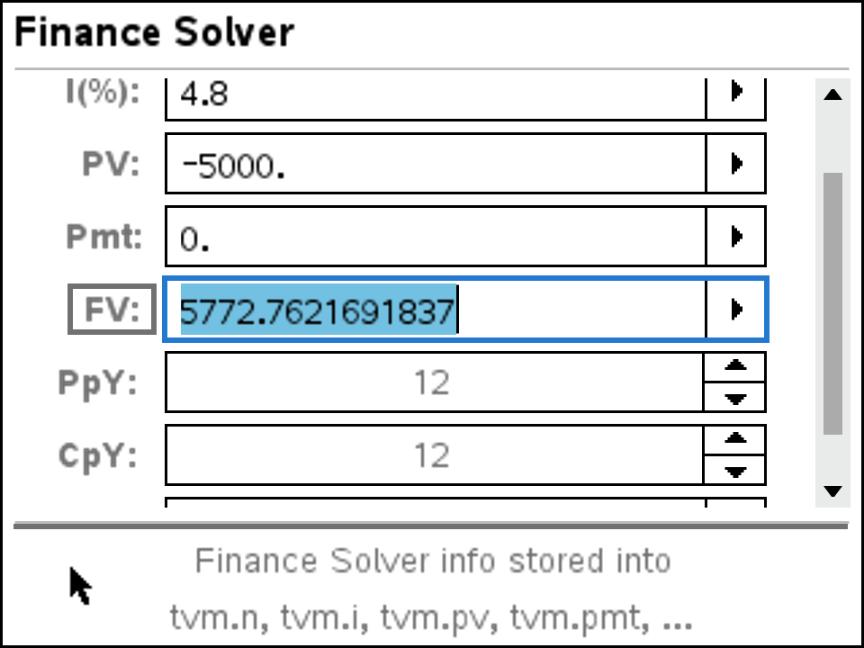
\(\mathrm{FV}=5772.762169\ldots\). Its positive sign represents savings returned to us.
Finish with the balance and the interest
(a) The balance is $5772.76.
(b) Interest earned \(=5772.762169\ldots-5000=\boxed{\$772.76}\).
Keep precision: use the unrounded output for the next calculation. On a Calculator page in the same problem, the saved value is tvm.fv; enter tvm.fv-5000. You can also re-enter the full calculation rather than a rounded result.